1. The Problem With Portal Leads
Most loan officers start mortgage lead generation by buying leads from portals. The borrower fills in one form and receives calls from four lenders within minutes. Many numbers are wrong, many borrowers are months away from applying, and the officer who calls fastest wins whatever is left.
The alternative is generating your own leads on Meta with a funnel that qualifies and verifies every borrower. The leads are exclusive, the data stays in your ad account, and the campaign gets better as it learns who actually funds. Every number below comes from our mortgage and insurance case studies.
2. What Verified Mortgage Leads Cost
| Campaign | Ad spend | Leads | Cost per lead |
|---|---|---|---|
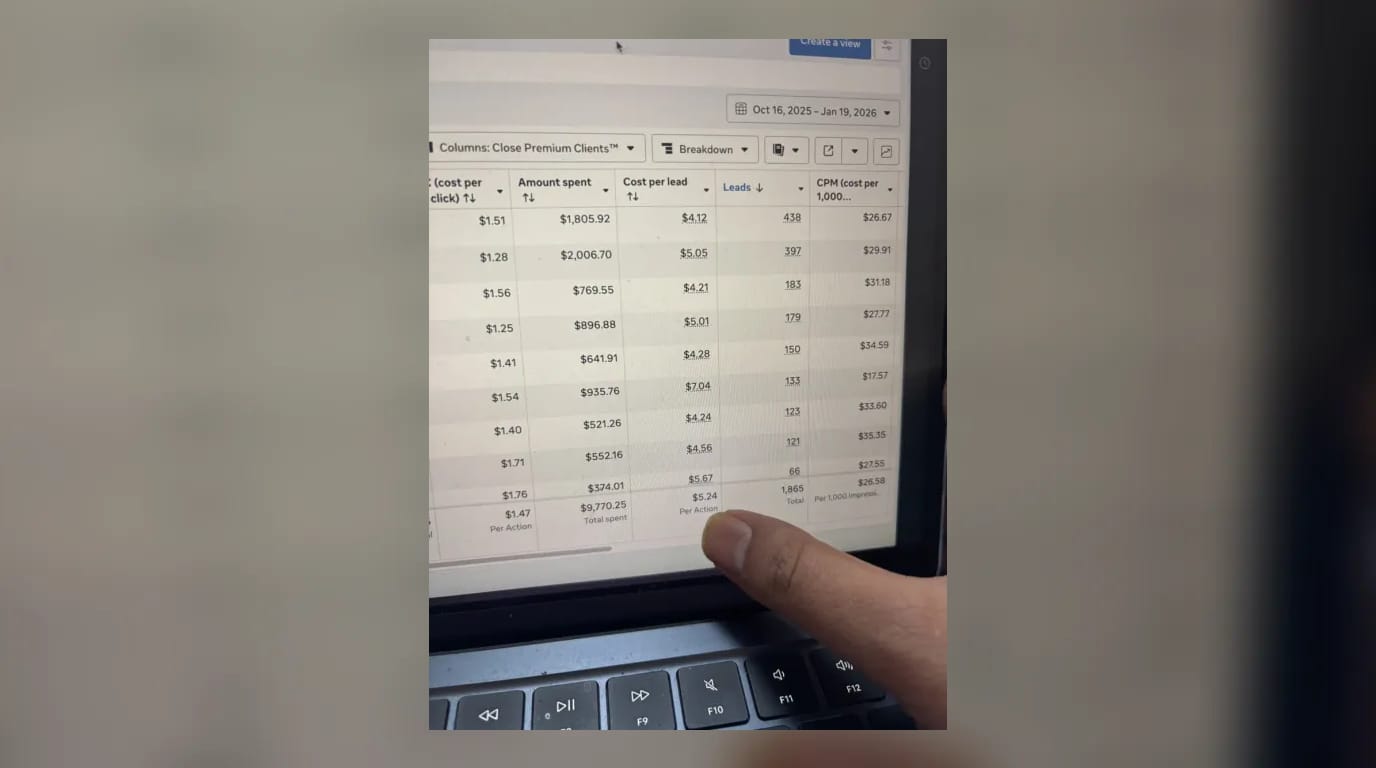
| Mortgage, 11-day testing phase | $612 | 142 | $4.31 |
| Mortgage-ready registrations, 1.72% CTR | $2,573 | 492 | $5.23 |
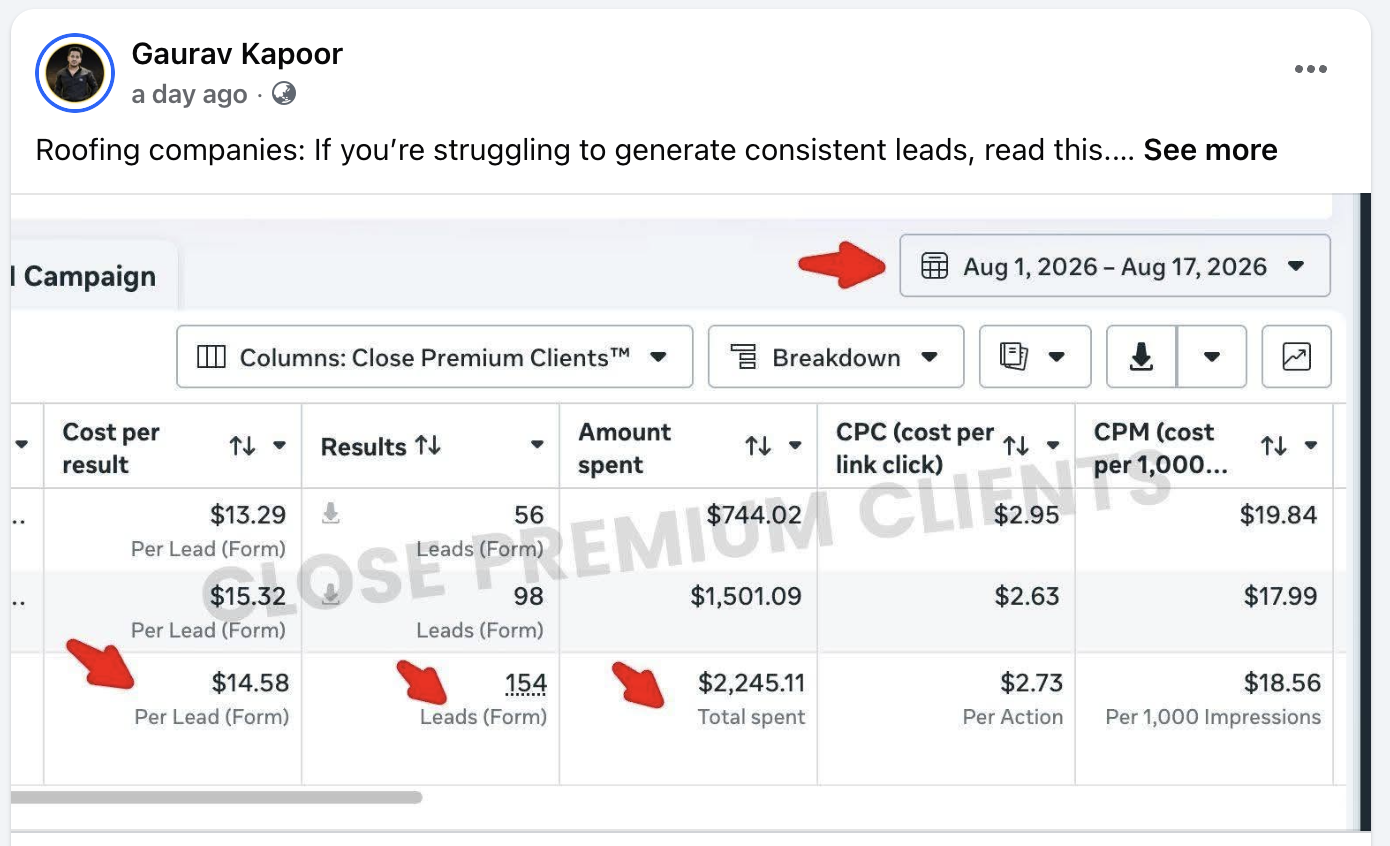
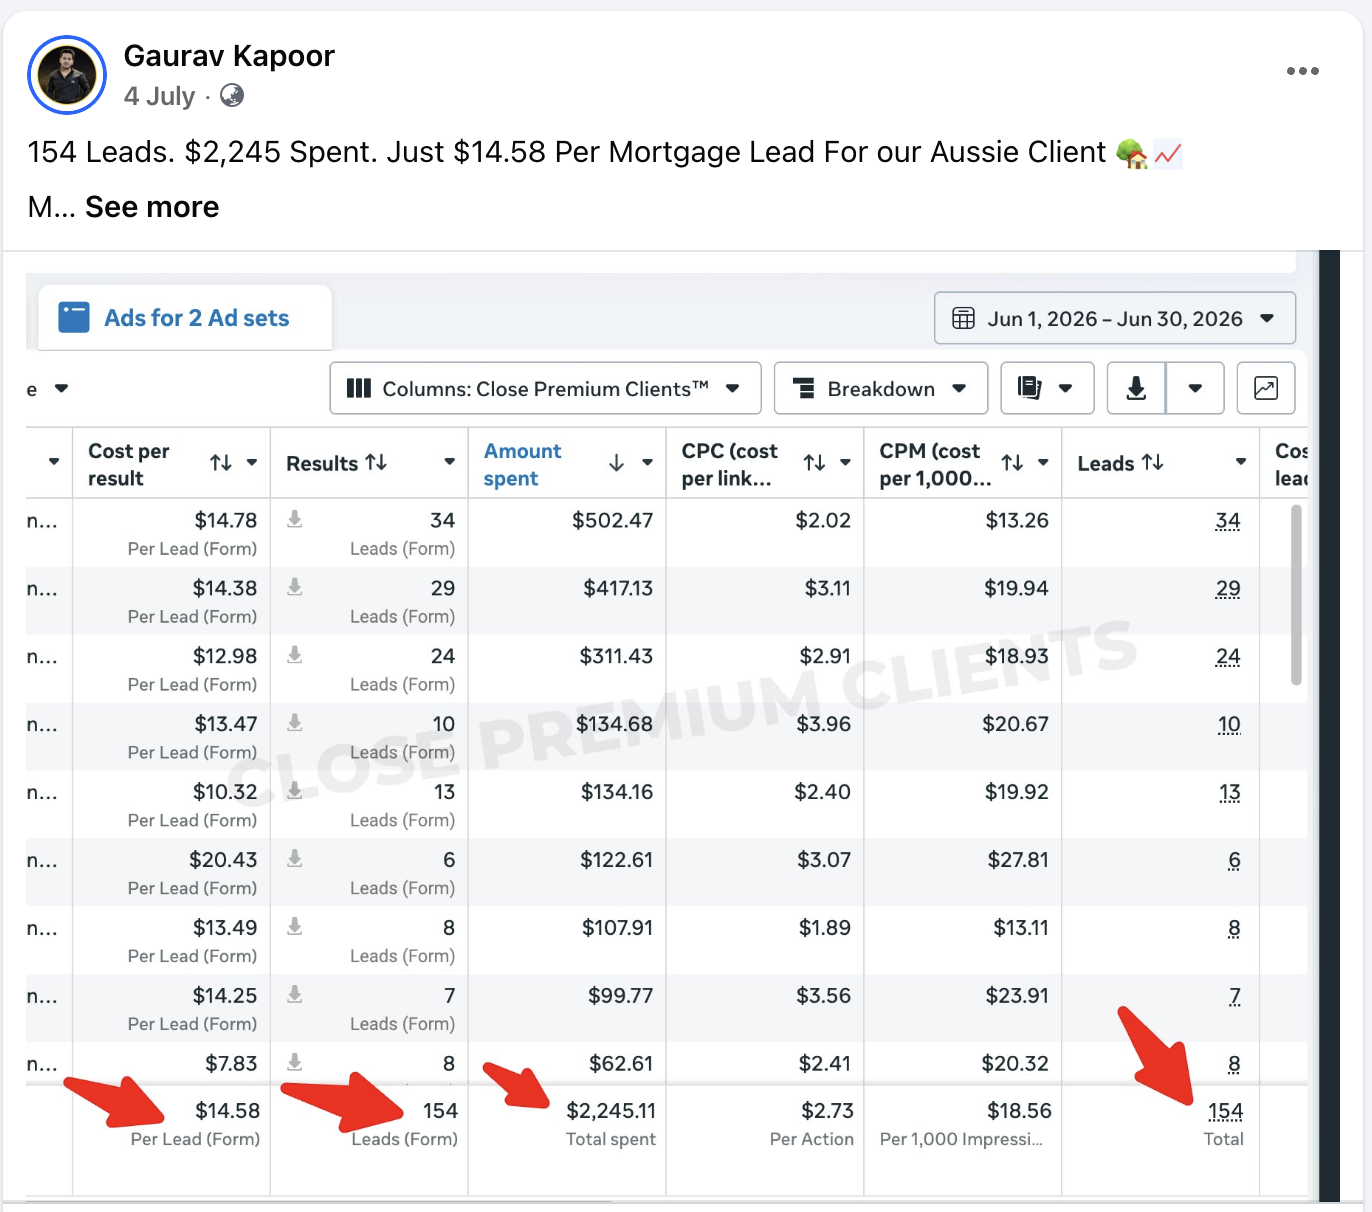
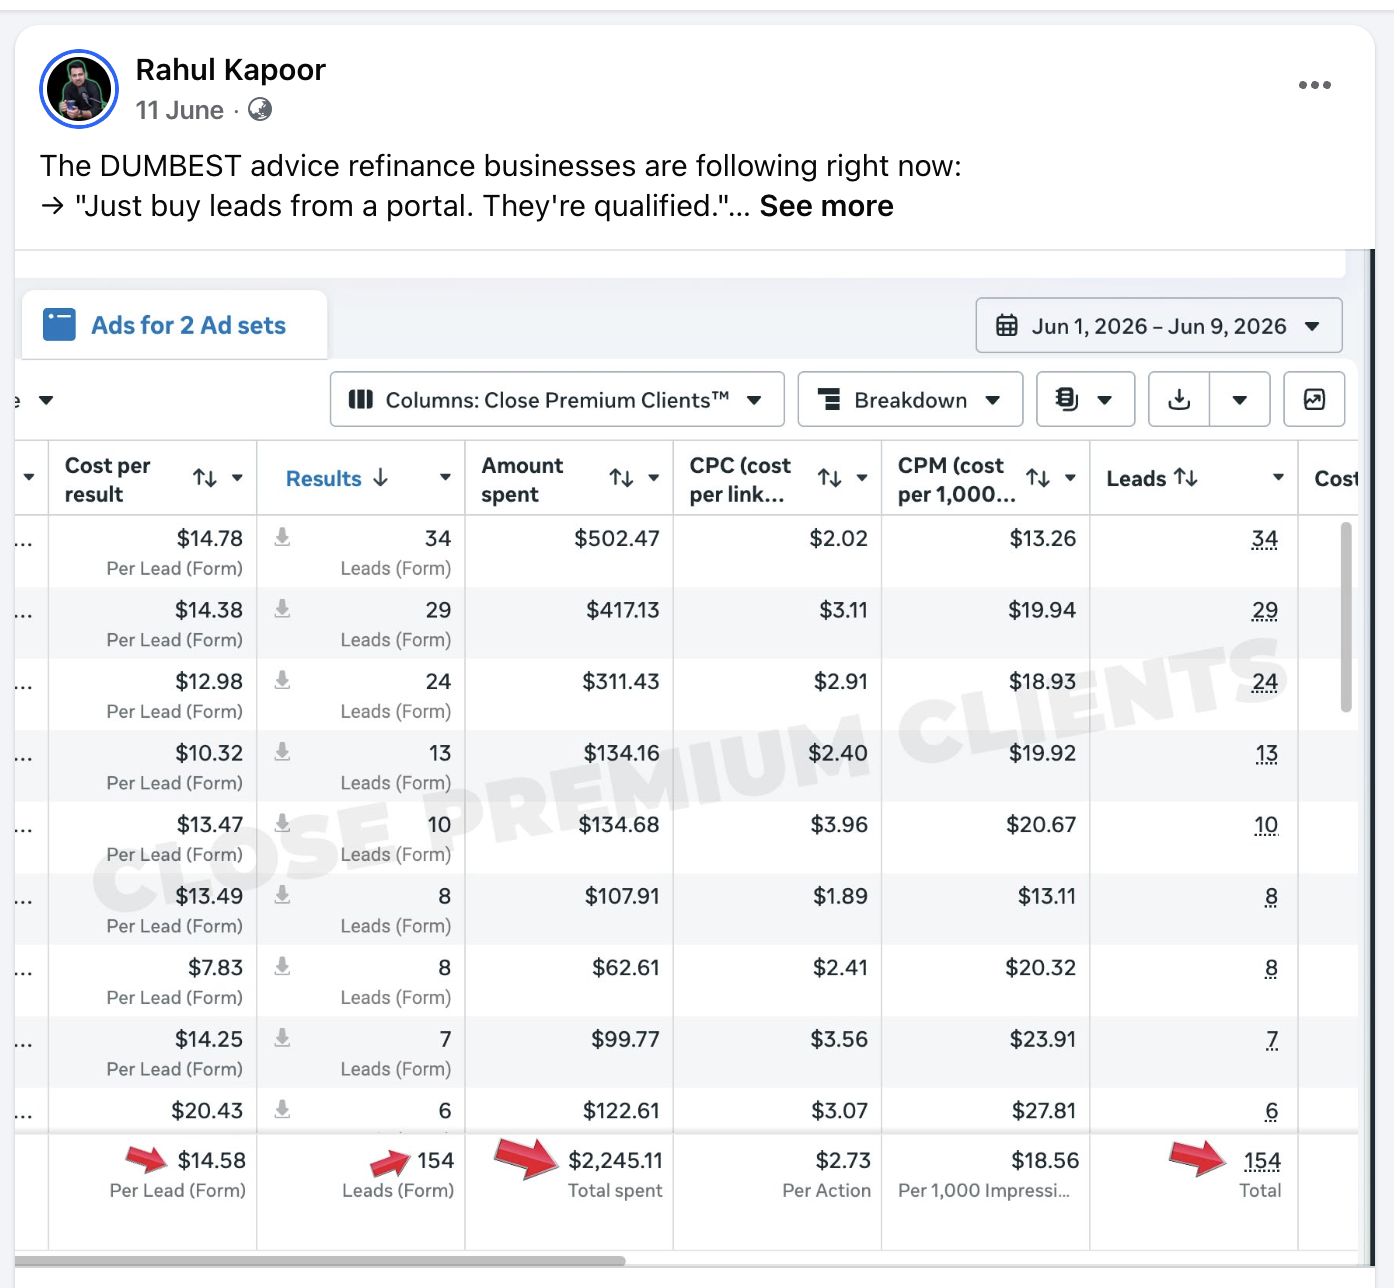
| Refinance, 9 days | n/a | 154 | $14.58 |
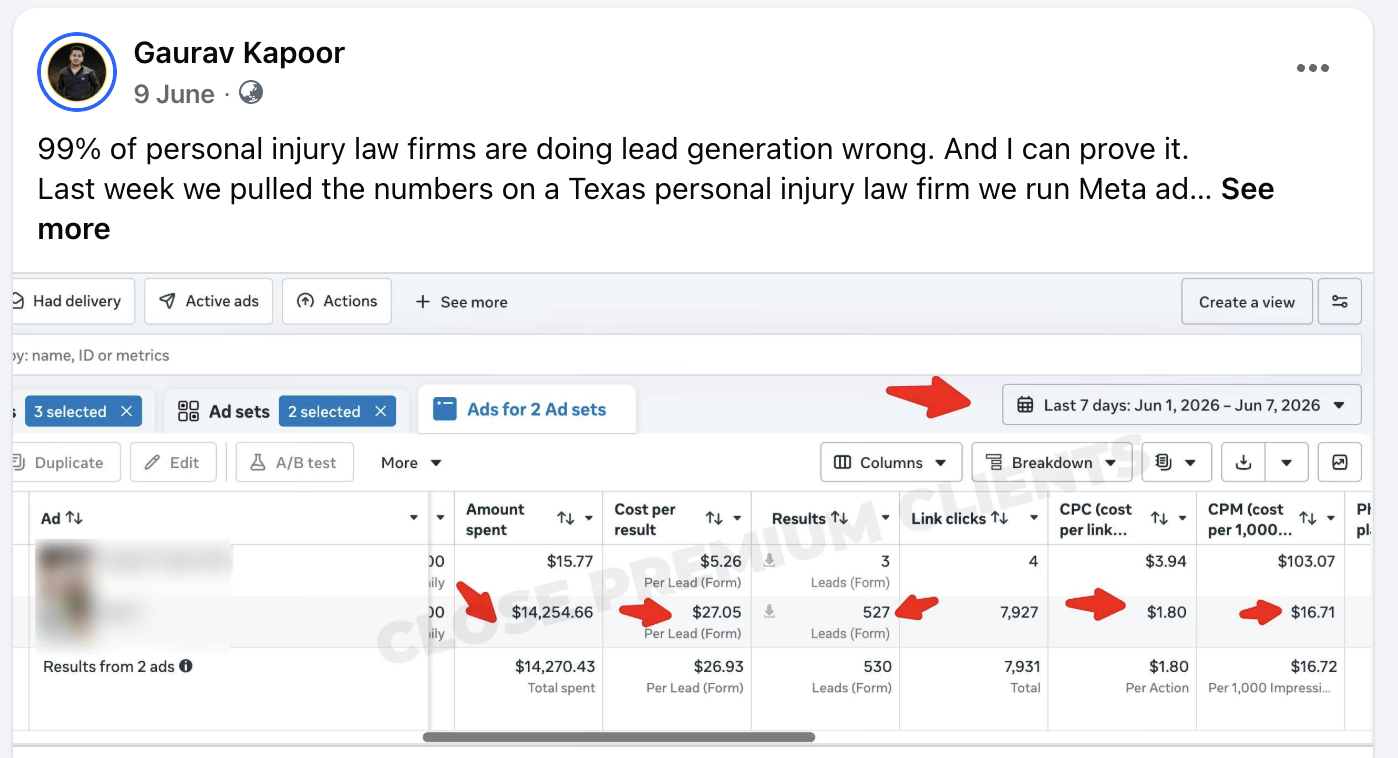
| Texas mortgage client | $19,725 | 823 | $23.97 |
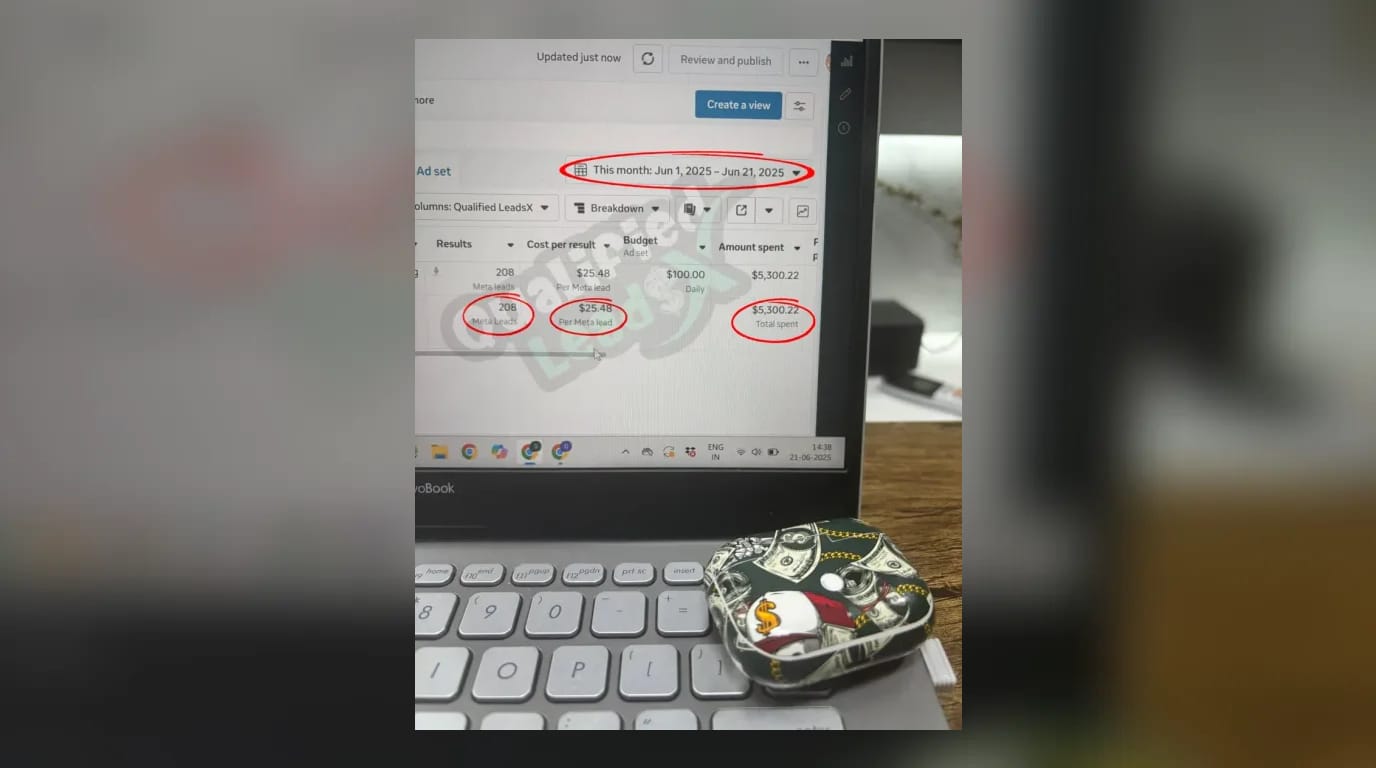
| Mortgage, 21 days, 37 closings | $5,300 | 208 | $25.48 |
The highlighted campaign is the one to study. Its cost per lead was the highest in the table, and it produced 160+ real conversations, 37 closed loans, over $9.2M in funded loans and more than $65,000 in commission in 21 days. Lead quality decided the outcome, not lead price.
208 leads, 37 closed loans, $9.2M funded
Every lead on that campaign verified their phone number before the form submitted. No fake numbers, no ghosting. Read the case.
3. Five Offers That Book Mortgage Appointments
The offer is the biggest lever in a mortgage ad. Each of these targets a different motivation, and we documented them as the offers that consistently boost appointments:
- Get pre-qualified in 5 minutes, no hard credit check. Removes the fear of a credit hit for cold purchase traffic.
- Refinance and save up to $500 a month, no closing costs. A concrete monthly number for owners with higher-rate loans.
- Get pre-approved in 24 hours. Speed for buyers who are already house hunting.
- Mortgage protection. Pays the mortgage if the borrower dies; a bridge between mortgage and insurance offers.
- Tap into your home's value, no fees. Cash-out for owners with equity and a specific need.
Match the offer to the audience's temperature. Cold audiences respond to low-commitment offers like the 5-minute pre-qualification; warm and retargeting audiences respond to pre-approval and refinance savings. The same thinking is covered in a recorded mortgage offer and ad copy strategy session.
4. The Funnel: Eligibility Questions and OTP
The landing page works like a short eligibility check, one question per screen: purchase or refinance, property value, current balance or down payment, credit band, timeline, then contact details. The answers route the lead: ready-now borrowers go straight to a loan officer, longer timelines go into a nurture sequence.
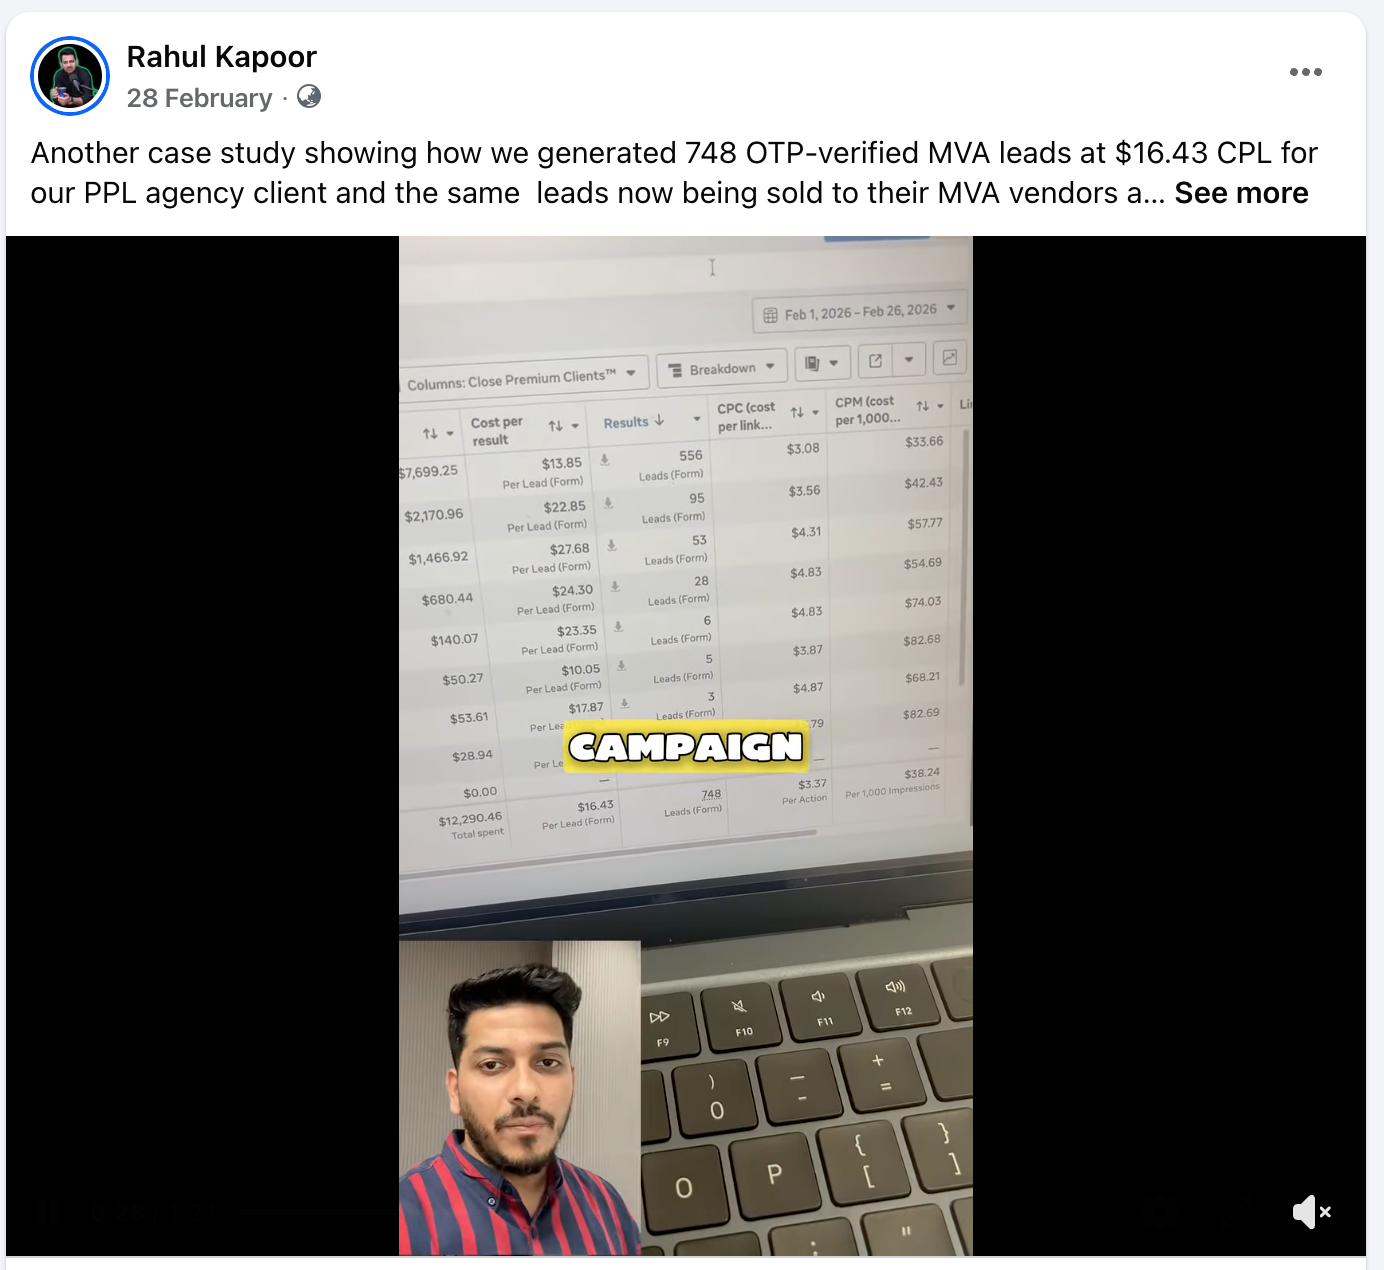
The final step sends a one-time code by text. The borrower types it in before the form submits, which removes fake and mistyped numbers. On the Texas campaign's 823 leads and the 154 refinance leads in 9 days, every lead was OTP-verified, so loan officers stopped wasting dials on numbers that never connect.
Meta treats housing and credit as special ad categories, which limits targeting by age, gender and location radius. The funnel's questions do the qualification the targeting no longer can.
5. Follow-Up: From Lead to Conversation
A verified borrower who does not hear back for an hour is shopping elsewhere. Run the 60-second follow-up stack: an instant text from the loan officer, an immediate call, and a voice agent for after-hours leads. Then book the consultation and protect it with the reminder sequence from our no-show guide.
Borrowers with longer timelines get a nurture sequence with rate updates and educational content, so they come back to you rather than a portal when they are ready.
6. The Same System for Insurance Agents
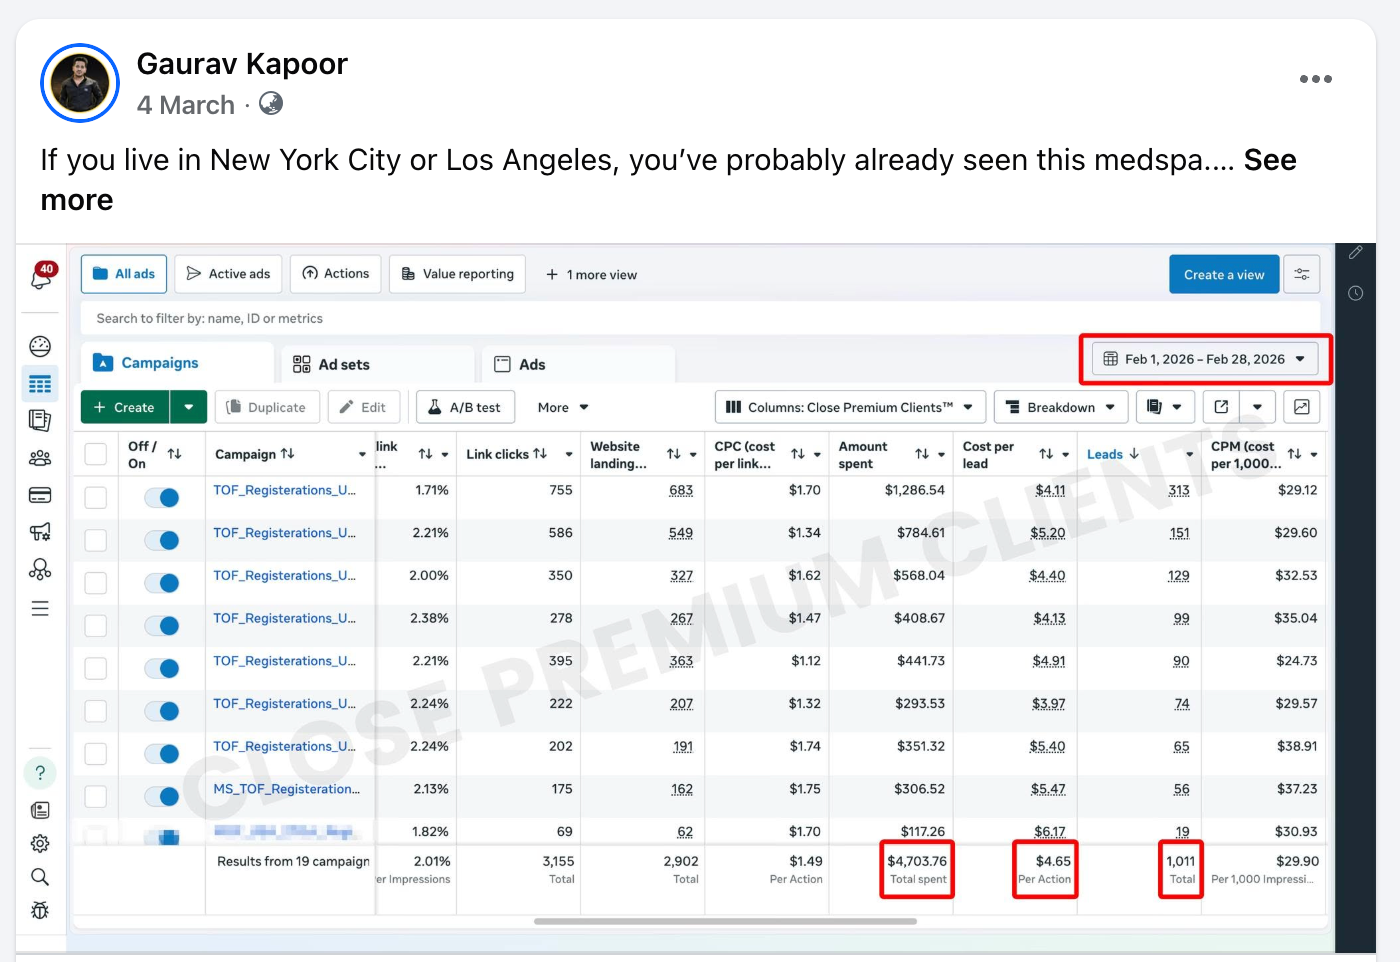
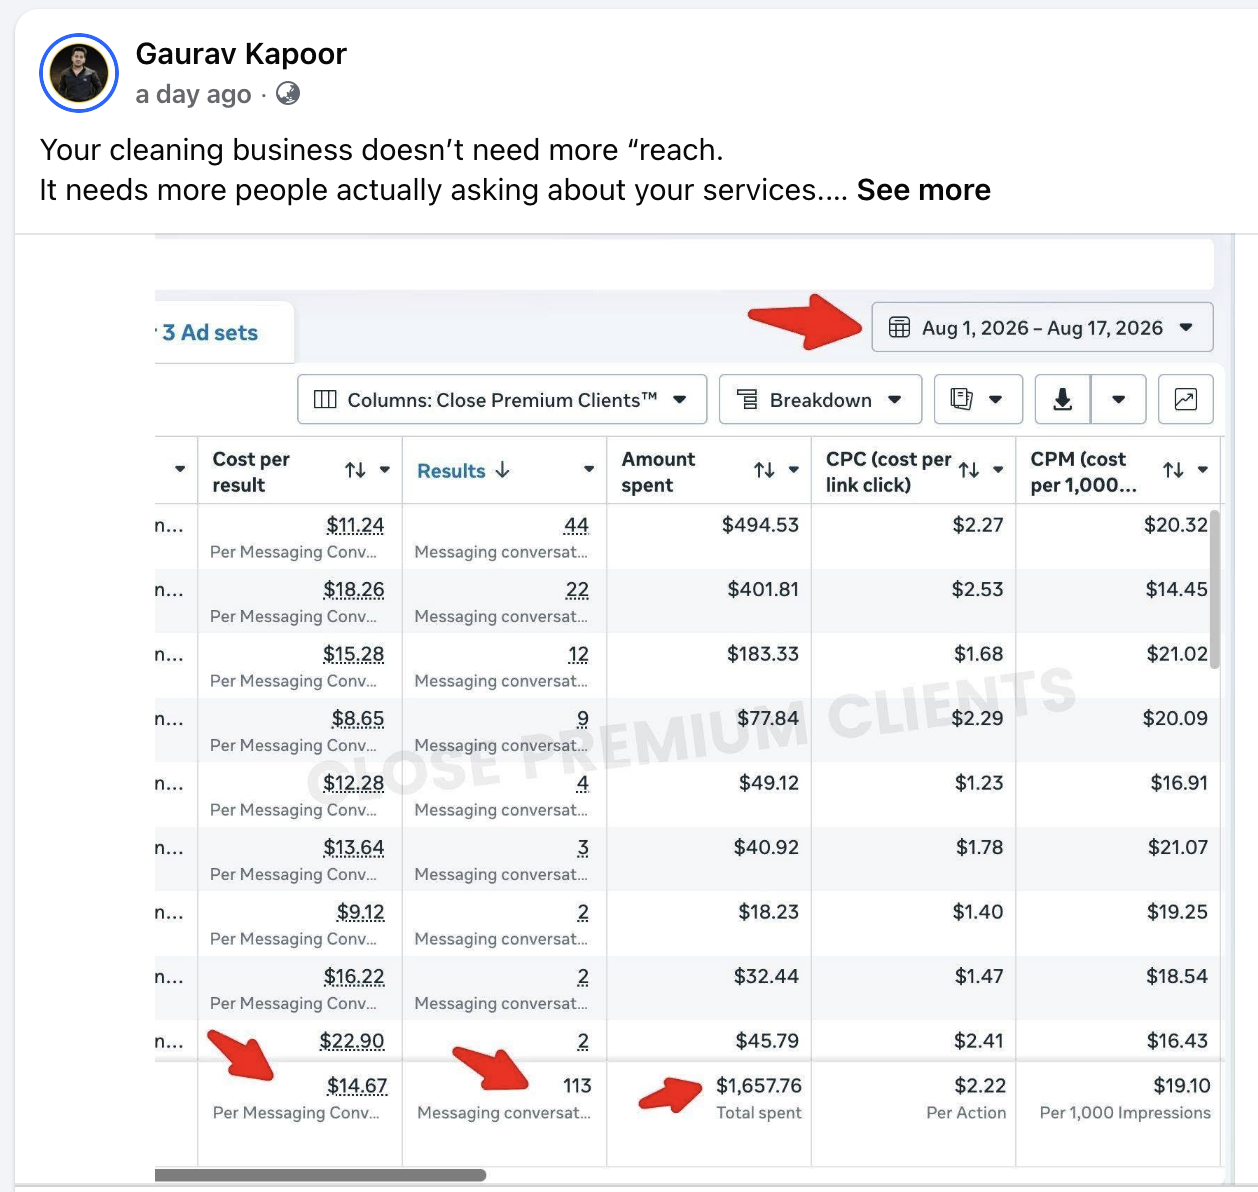
Final expense and life insurance follow the same pattern: a short qualifying funnel, verification and fast follow-up. One pay-per-lead client generated 2,440 final expense leads at $7.79 on $19,011.31 in a single month, and a smaller life insurance test produced 55 qualified leads from $990.
7. What to Measure
Track the ladder, not the lead: verified lead, conversation, application, approval, funded loan and commission. Send applications and fundings back to Meta through the Conversions API so the algorithm finds more borrowers who fund. The same discipline drives the results in our personal injury lead generation guide, where cost per signed case matters more than cost per lead.
All the campaigns above are on the mortgage and insurance case studies page. If you want this funnel built for your branch or brokerage, book a strategy call.
Results from this playbook
Verified client results built on the system in this article, with the numbers from the ad account and CRM.
- $65K+RevenueMortgage Case Study: $65K+ Revenue on $5,300 Ad Spend
- 492Leads generatedMortgage Case Study: 492 Leads at $5.23 CPL
- $388,000RevenueMVA Case Study: $388K Revenue on $20K Ad Spend
- 8,810Leads generatedMVA Case Study: 8,810 Leads at $7.61 CPL
All mortgage & insurance lead generation case studies · All MVA & personal injury lead generation case studies
Frequently Asked Questions
How much do mortgage leads cost on Facebook?
In our documented campaigns, OTP-verified mortgage and refinance leads cost between $4.31 and $25.48 each. The low end came from a small testing budget; at larger budgets in competitive states, $15 to $25 is a realistic range.
Are Facebook mortgage leads good quality?
They are when the funnel qualifies and verifies. Eligibility questions on loan type, value, credit band and timeline, plus OTP phone verification, mean every lead is a real borrower who asked to be contacted. One campaign's 208 leads produced 160+ conversations and 37 closed loans.
What is the best offer for mortgage ads?
It depends on the borrower's temperature. Fast pre-qualification without a hard credit check works for cold purchase traffic, monthly savings works for refinance, and home equity cash-out works for owners with equity. Test two or three at once.
Do I need to follow mortgage advertising rules on Meta?
Yes. Meta treats housing and credit as special ad categories with limited targeting options, and mortgage advertising is regulated. Have offers and disclosures reviewed for compliance before launch.
Gaurav Kapoor
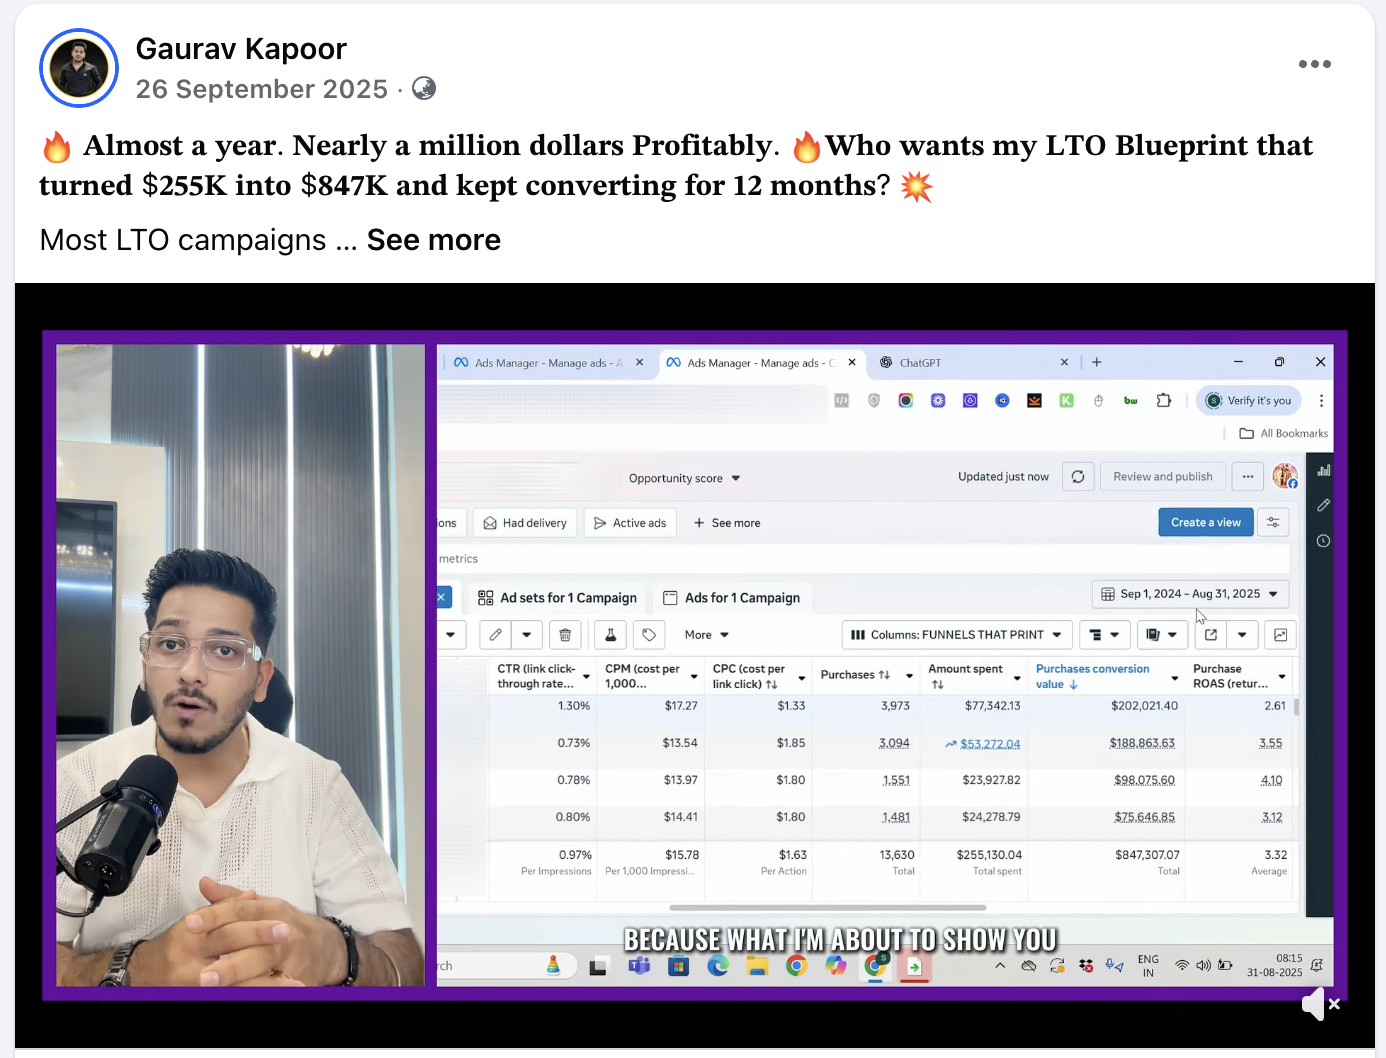
Founder of Funnels That Print. Since 2019 Gaurav has architected high-ticket and low-ticket acquisition funnels for coaching, consulting, home services, finance and DTC brands, including the $1.52M high-ticket consulting funnel and the $847K self-liquidating offer funnel documented on this site.
More from Gaurav ↗